
Can I Pay Off Equity Release Early
So, you're sipping your latte, staring at your equity release plan, and wondering, "Can I pay this off early?" Well, grab another biscotti, 'cause we're diving in!
First things first, what's equity release?
In a nutshell, it's like tapping into your home's equity - that's the value of your home minus any outstanding mortgage. You're basically saying, "Hey, I've paid off a chunk of my house, can I have some of that back, please?"
There are two main types: Lifetime Mortgages and Home Reversion. Lifetime Mortgages let you borrow against your home's value, while Home Reversion involves selling part of your home to a provider.
Must Read
Now, can you pay it off early?
That's the million-pound question, isn't it? The short answer? It depends.
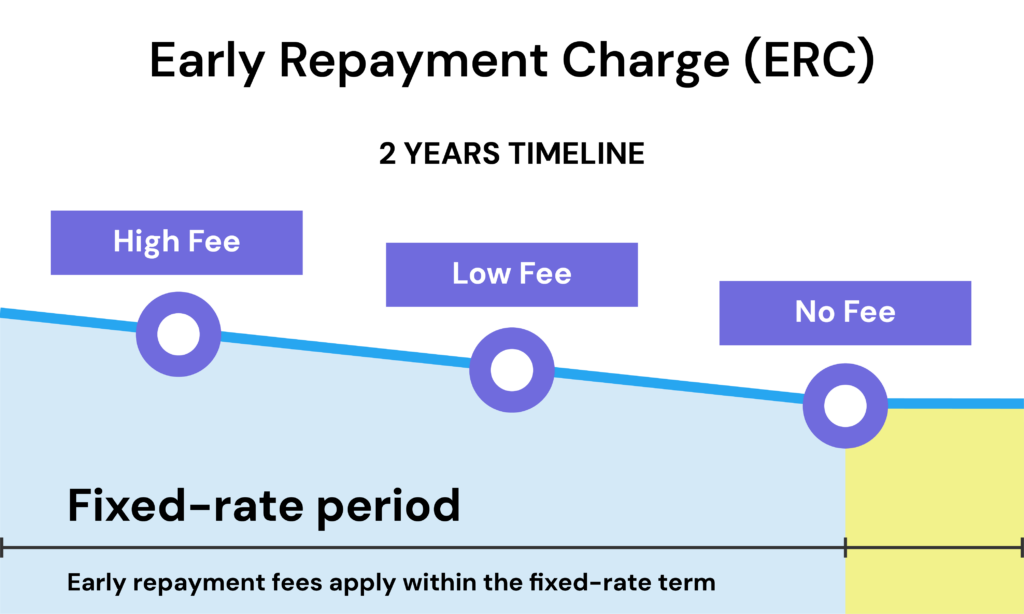
With Lifetime Mortgages, you usually can't pay off the loan early without incurring a hefty fee. These are often called early repayment charges, and they can be a real kicker. Some plans have them for the first 5-10 years, others for the entire term. So, it's like being in a relationship where you can't break up without paying a fortune. Not ideal.
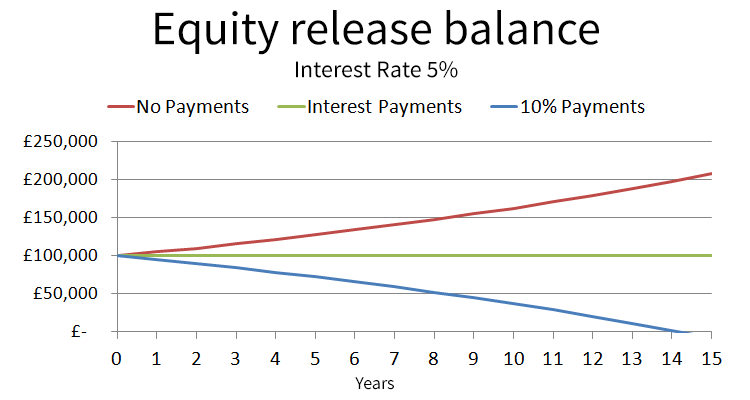
On the other hand, Home Reversion plans often let you pay off early, but there's a catch. You usually have to pay back the full amount, plus interest. So, it's like they're saying, "You want out? Fine, but it's gonna cost ya."
What about those pesky fees?
Fees are like the uninvited guest at a party - they're always there, and they can be a real buzzkill. With equity release, you've got setup fees, valuation fees, and sometimes even exit fees. They can add up to thousands, so it's worth asking, "What's in it for me?" before you dive in.

Some plans offer drawdown features, letting you take money out in chunks. This can help you avoid some fees, but it also means you'll pay interest on the entire amount you've borrowed, not just what you've taken out. It's like ordering a massive pizza, but only eating a slice - you're still paying for the whole thing.
So, should you pay off early?
That's a personal call, mate. If you need the money now, but think you'll have a cash windfall later, it might be worth it. But if you're just curious, it might be best to leave it be. Remember, equity release is a big decision, like choosing a life partner. You don't want to rush into anything you'll regret later.
Always chat with a financial advisor first. They're like your wingman, helping you make the right call. And hey, if you're still unsure, there's always the coffee shop. We'll be here, waiting with another biscotti.