
Could I Get A Mortgage On Benefits
Ever wondered if you can bag a mortgage while living on benefits? You're not alone. With the cost of living skyrocketing, it's natural to wonder if homeownership is still within reach for those relying on government support. So, let's dive in, shall we?
First Things First: The Basics
Before we get started, let's clear one thing up. Benefits, in this context, refer to state-provided financial aid like Universal Credit, Income Support, or Housing Benefit. These are designed to help cover living costs, including rent. Now, let's talk mortgages.
A mortgage is a loan from a bank or building society to buy a property. You pay it back, with interest, over a set period, usually 25 years. Sounds simple enough, right? But can you get one on benefits?
Must Read
Can I Get a Mortgage on Benefits?
Here's the thing: it's not impossible, but it's not easy either. Most lenders want to see a steady, reliable income. Benefits, while they provide crucial support, don't always tick that box. However, there are a few schemes designed to help people like you.
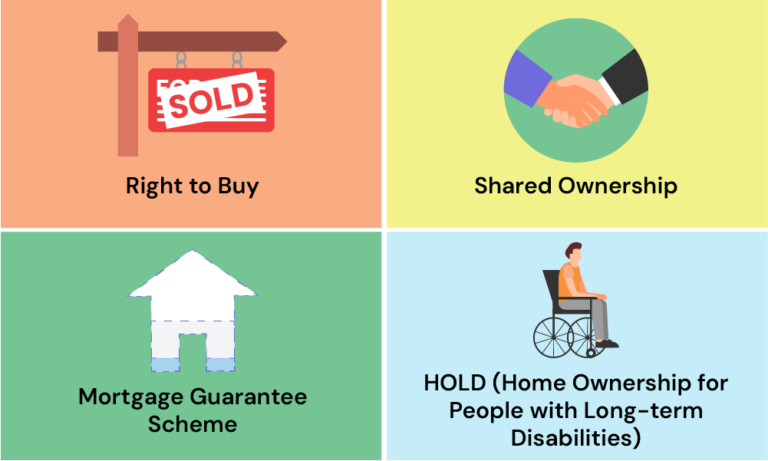
Shared Ownership
Shared Ownership is a scheme where you buy a share of a property (between 25% and 75%) and pay rent on the rest. It's a great way to get onto the property ladder, and it's open to people on benefits. The catch? You'll need a deposit (usually at least 5% of the share you're buying) and to pass the lender's affordability checks.
Help to Buy: Equity Loan
This scheme lets you buy a new-build home with just a 5% deposit. The government lends you up to 20% (40% in London) of the cost of a newly built home, so you only need a 75% mortgage. It's open to first-time buyers, including those on benefits, but you'll still need to pass affordability checks.
But What About Affordability?
Affordability is key when it comes to mortgages. Lenders want to know you can afford the repayments, and that's where things can get tricky for benefit recipients. Here are a few tips to boost your chances:
- Save, save, save: Every little helps. Even if you can only save a few pounds a week, it'll add up and show lenders you're serious about homeownership.
- Boost your credit score: Pay bills on time, don't max out credit cards, and register to vote. It all helps build a positive credit history.
- Consider a joint mortgage: If you have a partner or family member with a steady income, you could apply together. This can boost your affordability and increase your chances of getting a mortgage.
Fun Fact: Benefits and Homeownership
Did you know that, according to the Department for Work and Pensions, around 10% of homeowners receive some form of benefit? It's a myth that benefits and homeownership can't mix.
Reflection: Homeownership Isn't Everything
While it's natural to dream of owning a home, it's not the be-all and end-all. Renting has its perks too - flexibility, no maintenance costs, and the freedom to move without selling up. So, if you can't get a mortgage right now, don't despair. There are plenty of other ways to build a happy, stable life.
Remember, homeownership is just one piece of the puzzle. Your worth isn't measured by your mortgage status. You're more than your benefits, and your home is just one part of your story.