
Does Universal Credit Count As Income For Mortgage
So, you're thinking about diving into the world of mortgages, huh? Well, grab a cuppa, 'cause we're gonna chat about whether that Universal Credit you're getting counts as income for your mortgage application. Spoiler alert: it's not as simple as a yes or no.
First things first, what's Universal Credit?
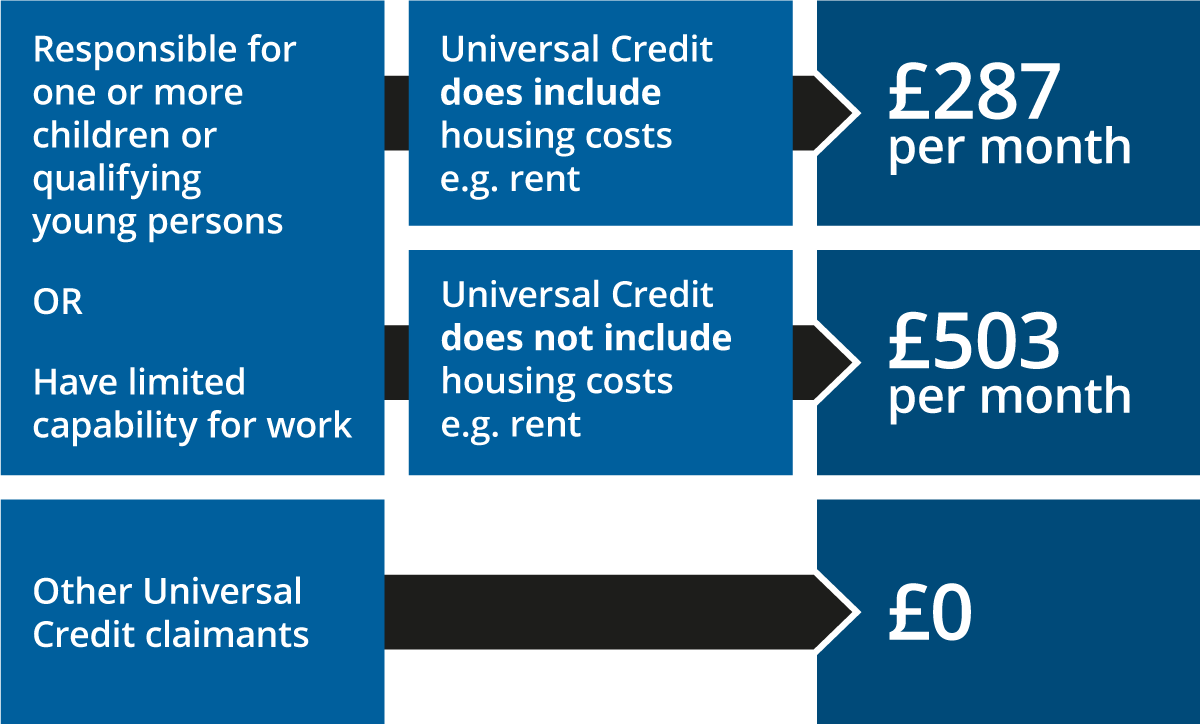
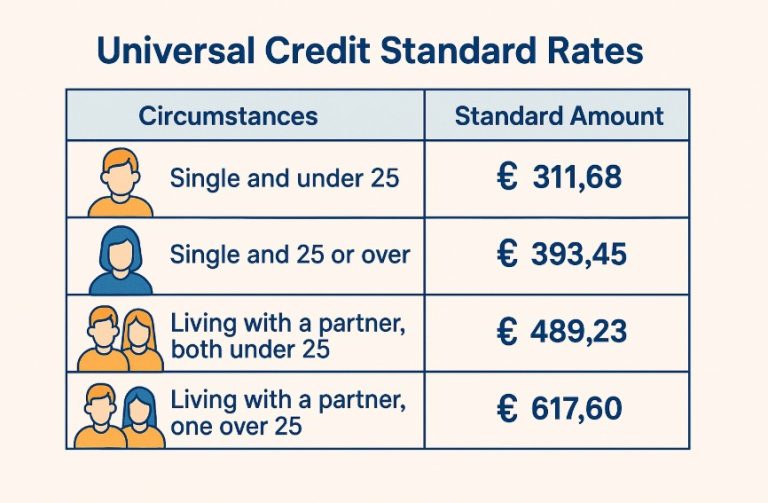
If you're new to the game, Universal Credit is a payment to help with your living costs. It's for people who are on a low income, out of work, or can't work. It's like the government's way of saying, "Hey, we've got your back, at least a little bit."
Now, let's talk mortgage.
When you're applying for a mortgage, lenders wanna know you can afford to pay back what you're borrowing. They look at your income, your outgoings, and whether you've got any debts. It's like they're playing a game of 'Can You Afford This House?'
Must Read
So, does Universal Credit count as income?
Here's where it gets a bit tricky. Some lenders might count it, some might not. It's like they're playing 'Universal Credit Roulette'.
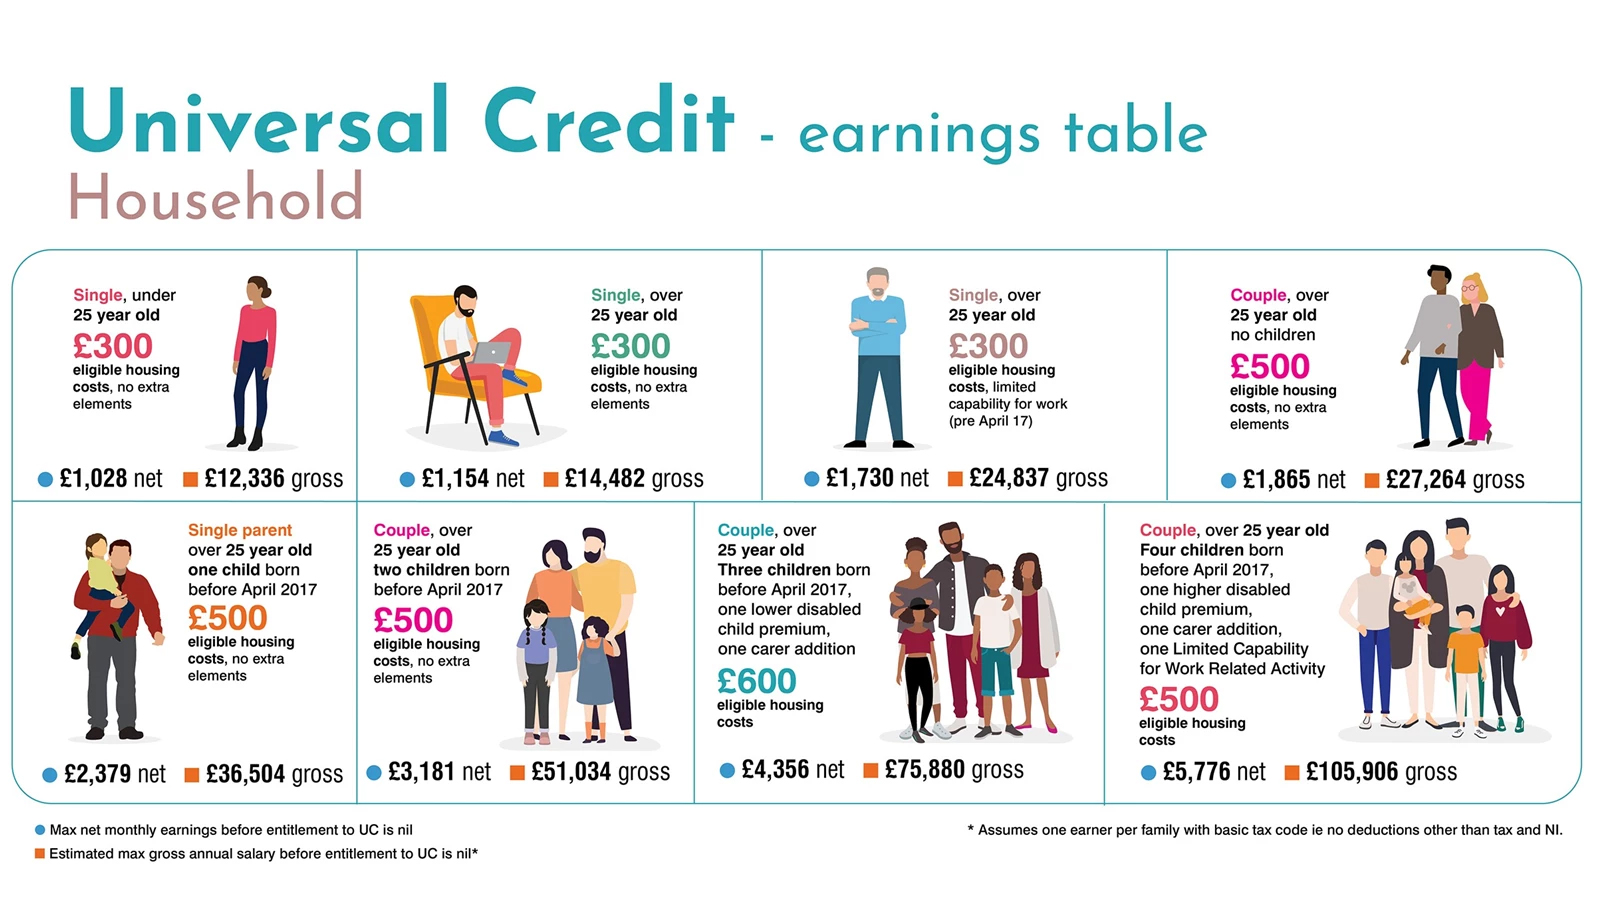
Some lenders might consider a portion of your Universal Credit as income, especially if it's helping with housing costs. But others might not count it at all, because they think it's not reliable enough. It's like they're saying, "Universal Credit? More like Unreliable Credit!"
But wait, there's more!
Even if a lender does count your Universal Credit, they might not count the whole thing. They might take off a chunk for tax, National Insurance, or other deductions. It's like they're saying, "Here's your Universal Credit, now give us some back."
What can you do?
First, don't panic. It's not the end of the world if your Universal Credit doesn't count as income. There are other ways to prove you can afford a mortgage.
Talk to a mortgage advisor. They're like the wise old owl of the mortgage world. They can give you advice tailored to your situation. They might know a lender who's more likely to count your Universal Credit, or they might have other ideas to boost your affordability.
And remember, it's not just about income. Lenders look at other things too, like your credit score, your deposit, and how much you've got left over after paying your bills. So, make sure you're on top of all that too.
So, should you apply for a mortgage with Universal Credit?
It depends. It's like asking if you should order the spicy noodles when you're not sure if you can handle the heat. Some people can, some people can't. It's all about knowing your limits and playing it smart.
If you're thinking about it, talk to a mortgage advisor first. They can give you the lowdown on whether your Universal Credit will count, and what you can do to boost your chances of getting a mortgage.
And that's a wrap!
So, there you have it. Universal Credit and mortgages - it's a bit of a minefield, but with the right advice, you can navigate it like a pro. Now, who's ready for a refill?